Underwriting, in plain words
Underwriting means deciding if a loan makes sense. The underwriter reads the file and weighs the risk. In commercial deals, the business is the borrower, not just the person.
Green-industry files have their own shape. Here is what we see most.
Seasonal cash flow is normal
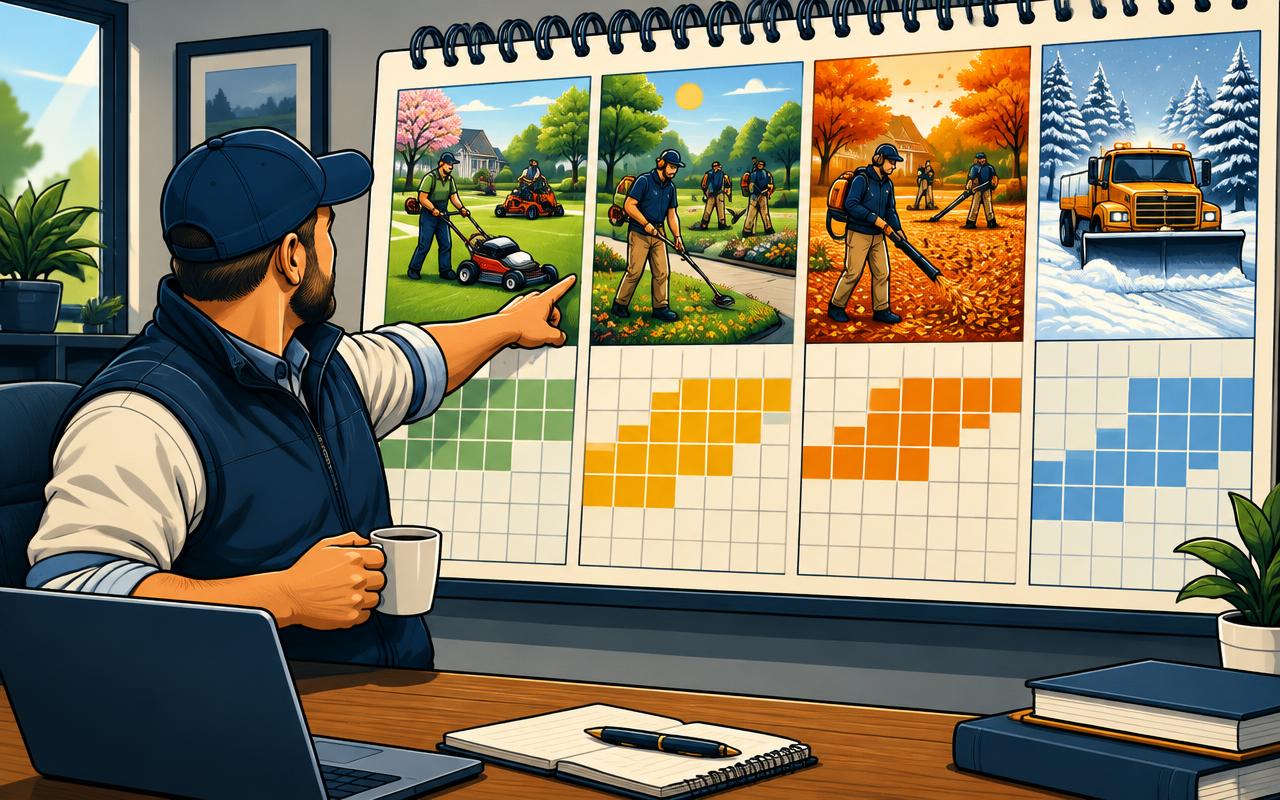
Landscaping income follows the weather. Spring and summer are busy. Winter can be slow. Some firms do snow work. Others save up during the season.
A thin bank statement in January is not always a red flag. It may just be February's job list. A good file explains the season instead of hiding it.
The machine is part of the answer
In equipment finance, the machine matters. It has value if the deal goes bad. That value backs the loan.
So the file needs the machine's details. Make, model, year, hours, and condition. A lien check matters too. A lien is a legal claim on the machine from an old loan. Nobody wants to finance a machine that someone else still claims.
Young businesses are common
Many green-industry companies are young. The owner may have ten years on crews and one year as a boss. That mix is normal here.
A strong file shows both. The work history and the new company's records. Down payment size and signed contracts help too.
What helps a file move fast
Speed comes from completeness. The files that move fastest have the same things in common.
- A clear machine quote or bill of sale with a serial number
- Recent bank statements that match the story
- Honest notes about past credit problems
- A short explanation of how the machine earns money
The decision is yours
We build the file. We do not grade it. Every approval, decline, and condition comes from the funder. Our job is to make the file worth your time.
Landscaping Equipment Financing LLC is an independent commercial equipment finance broker, not a lender. All financing is subject to lender approval. This article is general information, not an offer or a quote.