Programs · Second look
Imperfect credit, told straight.
Good owners sometimes have a past credit bump. If a lender’s rules allow that risk, we tell the full story. If no lender’s rules fit, we say so.
Original AI illustration · unbranded · not a real customer or funded deal
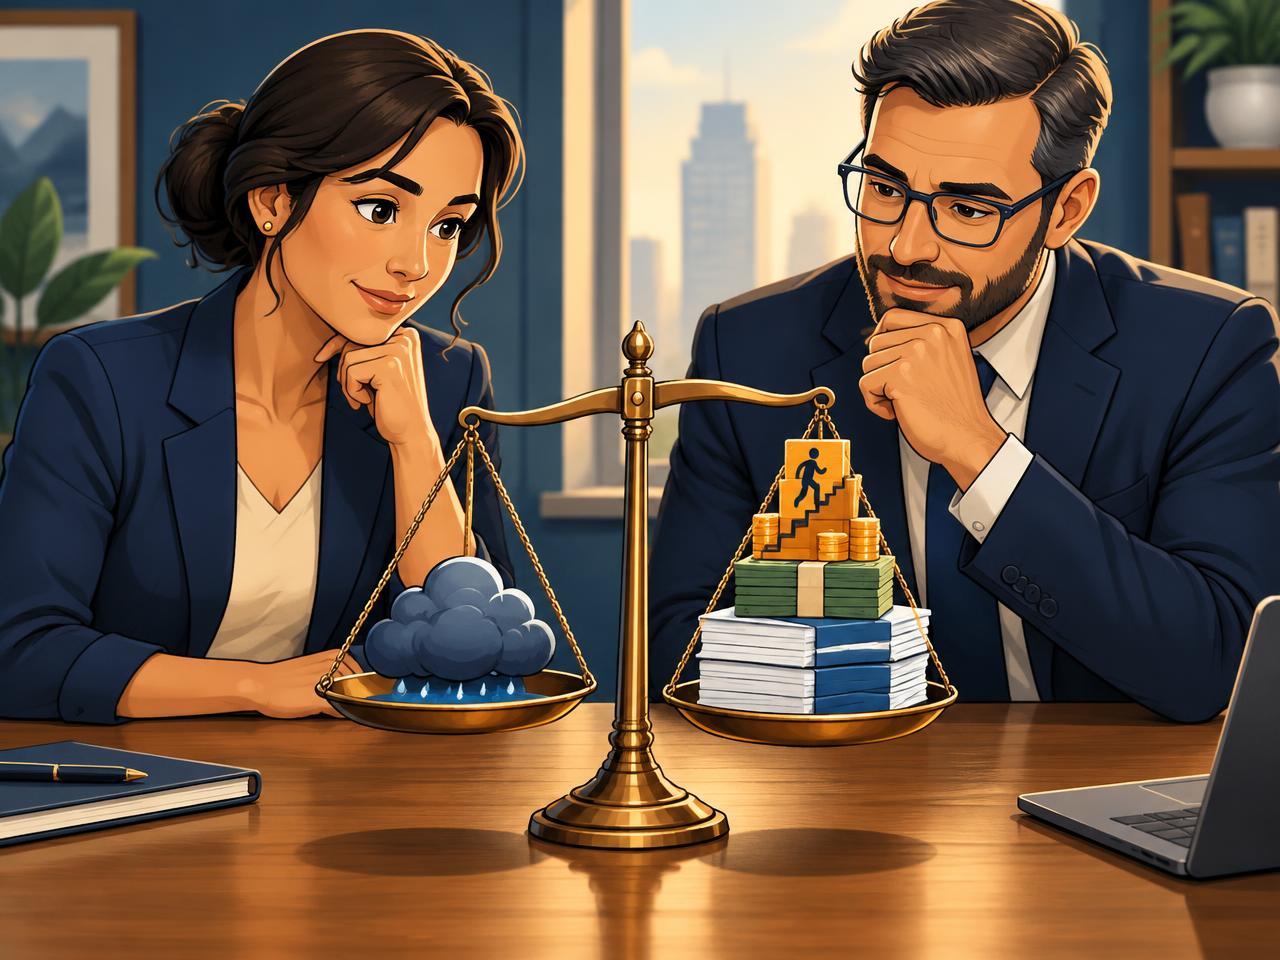
Fair review
A past bump. Real strengths.
We show the problem and the good facts side by side. Cash, down payment, years in work. You decide.
Original editorial illustration
Working businesses
Many have steady jobs.
A tree crew can have full calendars and an old credit issue. Both facts belong in the file.
Original AI illustration · unbranded · not a real customer or funded deal
Tier matching
A, B, C and D — mapped to your rules.
A
Clean history
B
Minor issues
C
Thin or bruised
D
Serious challenges
What we add
Compensating factors, stated plainly.
- 01
The ‘why’ behind the credit
A short, borrower-provided explanation, labeled as stated — not verified. - 02
Down payment available
If the borrower can put money down, we note it. - 03
Equipment strength
Machine type, age and resale context in plain words. - 04
Business proof
Time in business, contracts or bank activity — when the borrower supplies it.
Lenders keep every decision. We never promise approval, and we never send a file to a funder whose program doesn’t accept that tier.
Next step